Loveland Housing Market Report (Updated Monthly)
Loveland's single-family supply fell from 3.9 months to 3.0 in a year, and its median went nowhere: $528,750 year to date, against $530,000 a year earlier. Tightness and price are different variables, and Loveland shows it plainly. Why the move-up band above the median behaves differently again.
Last updated: October 2026. Figures are single-family sold data for the city of Loveland, from the Colorado Association of REALTORS Local Market Update (data from IRES, the Front Range MLS): the latest release is August 2026, stamped current as of September 3 (the September update is expected in late October).
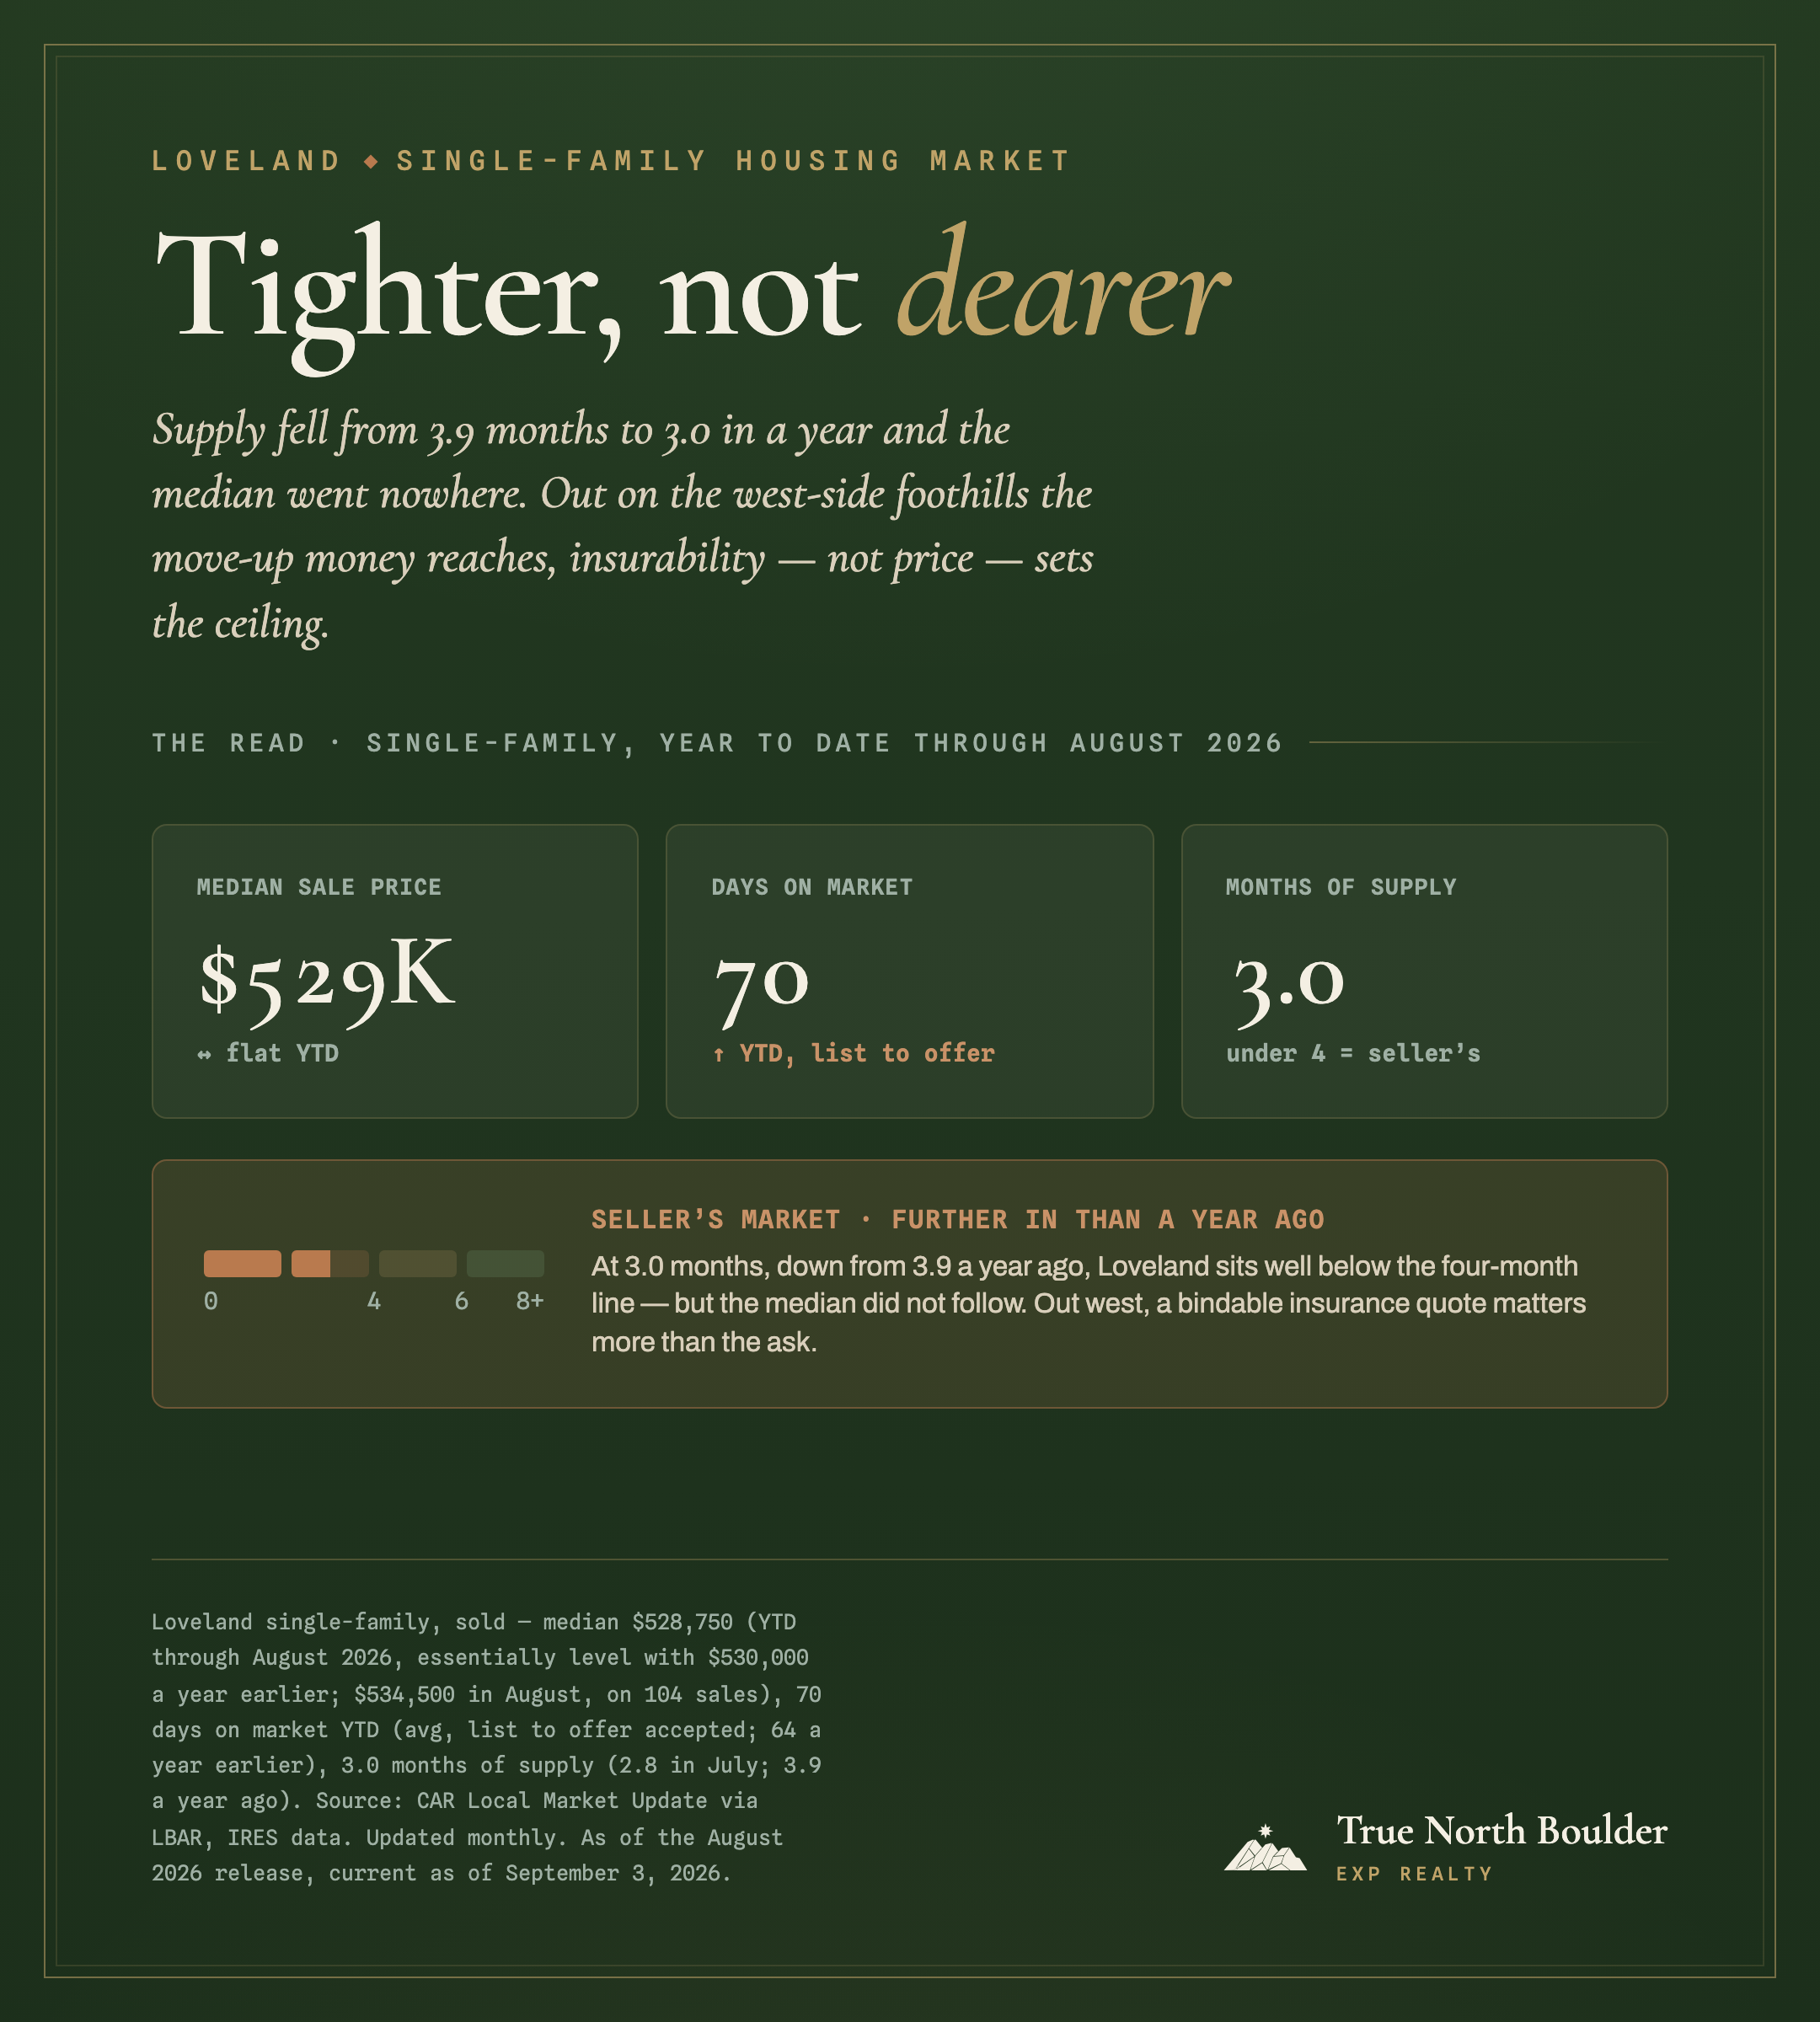
Loveland's single-family supply fell from 3.9 months to 3.0 in a year, and its median did not move: $528,750 year to date through August 2026, against $530,000 for the same stretch last year (CAR/IRES). That pairing is the whole point of this report. A market can get materially harder to buy in without getting more expensive, because supply measures how fast the shelf clears and a median measures the middle of what happened to sell. Loveland is a clean demonstration that those are two different variables.
The footnote that matters more for a move-up buyer: the $800K–$1.5M band trades well above Loveland's $528,750 median, in the upper tail of the distribution, so the town figure tells you Loveland is affordable and busy, not what your band actually costs.
What's the Loveland median right now?
Loveland single-family closed at a median of $528,750 year to date through August 2026, essentially level with the same stretch last year ($530,000). Lead with the year-to-date figure; a single month here rests on about 100 sales and swings. August printed $534,500 on the month, against $539,900 in August 2025, while the year-to-date line has sat within a few thousand dollars of $528,000 all summer. The year-to-date average, $610,332, sits well above the median, which tells you the upper end (the west-side foothills and lakeshore stock) pulls the top of the market up.
Read those figures the way we compile them: single-family, sold, city of Loveland, and note the one number we deliberately won't publish.
The town median sits below your band
Every figure here is single-family, sold, for the city of Loveland, from the Colorado Association of REALTORS Local Market Update, built on IRES MLS data and published free each month. Medians, averages and percent-of-list all exclude seller concessions.
We won't publish a months-of-supply figure for the $800K–$1.5M band. Half of Loveland's single-family sales close below $528,750, so a move-up buyer shops the upper tail of the town's distribution, where inventory is thinner, homes are more distinctive, and the market is likely slower and choosier than the busy 3.0-month town aggregate suggests. No public source breaks the band out; it takes a direct IRES pull. If you're transacting in that band, ask us to pull yours; a band-level read on the upper-tail inventory your own search faces beats a town aggregate that was never about your house.
If supply tightened this much, why didn't the price move?
Because tightness and price direction are different variables. Loveland's supply fell by almost a full month in a year, and its year-to-date median sits within a quarter of a percent of last year's. The corridor around it tells the same story from other angles: Boulder's year-to-date median is flat ($1,299,900 against $1,300,000) and Longmont's is down about 2.4%, while all three towns have less supply than a year ago. Tightness tells you how fast the shelf clears; it doesn't dictate which way the median moves.
There's a wrinkle that makes Loveland worth watching. Its supply fell while its time to an offer rose: 70 days year to date, against 64 a year ago, and 72 in August against 65 a year earlier. Longmont sold faster than a year ago (57 days against 59) and Boulder took about as long (72 against 70). A shorter shelf that takes longer to clear usually means fewer homes listed rather than more buyers chasing them, which is consistent with a flat median.
Still, hold the same line we hold everywhere. A flat median is the price of what sold, not proof that a given home is worth what it was a year ago. A town median moves with the mix of what traded. For value versus mix, the FHFA publishes two quarterly repeat-sales indexes for the Fort Collins-Loveland metro (Larimer County), which follow the same homes over time; they can disagree in a single quarter, so read them over a full year. And one number you'll see quoted, homes sold at about 99.0% of list price in August, is measured against the last list price, after any reductions, and excludes seller concessions, so it's evidence that homes which sell close near their final ask, not that every list holds.
Is Loveland a buyer's or a seller's market?
A seller's market, and further into one than a year ago. Loveland supply is 3.0 months, down from 3.9 a year ago and up from 2.8 in July. ShowingTime, the firm behind the CAR reports, reads supply under four months as favoring sellers and four to six as balanced, and the label measures speed, not price. A year ago Loveland sat barely under four; now it sits well below that line. Boulder, by contrast, sits at 4.2, inside the balanced band. We won't call Loveland or Longmont "the tightest": at 3.0 and 2.8 they are one cluster, they have run within about three tenths of a month of each other since May, and the order has swapped more often than not.
| Single-family | Loveland | Longmont | Boulder |
|---|---|---|---|
| Median, year to date through August 2026 | $528,750 | $610,000 | $1,299,900 |
| Median YTD, against the same stretch last year | about −0.2% | about −2.4% | flat |
| Months of supply, August 2026 | 3.0 (from 3.9) | 2.8 (from 3.5) | 4.2 (from 5.4) |
| Days on market, year to date | 70 (from 64) | 57 (from 59) | 72 (from 70) |
Colorado Association of REALTORS Local Market Updates; data from IRES, single-family, sold, August 2026 and year to date through August 2026, with the same stretch of 2025 in brackets. Town-level figures, not band-level. Loveland and Longmont are within 0.3 months of each other and have been since May; read that as one cluster, not a ranking.
For a move-up buyer, the corridor trade matters: selling in Boulder to buy in Loveland means selling into the looser market (4.2 months of supply) and buying into the tighter one (3.0 months), the harder direction, though on time to an offer the two now run close, 72 days against 70 year to date. The money has to be settled before you write. We work the financing in bridge loan vs. sale contingency and the sequencing in the buy-before-you-sell playbook.
In Loveland's move-up band, insurance is the number the median hides
The west-side foothills, canyon-mouth, and Lake Loveland stock a move-up dollar reaches is the same ground that carries wildfire and flood exposure, and on those homes insurability (whether a carrier will bind coverage, and at what cost) can decide the deal before price does. A newer east-side home in a metropolitan district trades that hazard premium for a metro-district mill levy on the tax bill instead. Neither shows up in a town median. Price both the insurance and the mills for the specific parcel before you fall for it; the Loveland market and neighborhood hub walks through how.
The honest take
Loveland spent the first half of this year reading like the easy corridor story, and the summer retired half of it. The supply side is real: 3.9 months to 3.0 in twelve months is a genuine tightening. The price side is not: the year-to-date median is flat, within a quarter of a percent of where it sat last year. A market can get harder to buy in and no more expensive at the same time, and this is what that looks like. Anyway, the town level isn't your level. The move-up dollar in Loveland lands on the west side, in the upper tail above the $528,750 median, where inventory is thinner and choosier than a 3.0-month town aggregate suggests, and where insurability, not price, is the constraint that actually ends deals. Don't shop it off the town median, and don't fall for a foothills house before you've priced the insurance on it.
We won't publish a band number. We will build your comp set.
A comp set at your price and your product, not a town average; on the west side, the insurance picture too. That's the honest answer to what a Loveland home is worth.
Frequently asked
What is the median home price in Loveland?+
Loveland's single-family median sale price was $528,750 year to date through August 2026, essentially flat against $530,000 for the same stretch last year (Colorado Association of REALTORS Local Market Update, data from IRES). The August month median was $534,500. That is the single-family figure a move-up buyer transacts on. Loveland townhomes and condos are a separate market. The $800K–$1.5M move-up band trades well above the town median, in the upper tail of Loveland's distribution, so the town figure understates what that band costs.
Is the Loveland housing market a buyer's or a seller's market?+
A seller's market on the scale ShowingTime uses, and tighter than Boulder. Loveland single-family carries 3.0 months of supply in August 2026, down from 3.9 a year ago (CAR/IRES). ShowingTime, which prepares the CAR town reports, counts anything under four months as a market favoring sellers, so Loveland was only just inside that band a year ago and sits well within it now. Homes sold at about 99.0% of last list price in August (the final asking price after any reductions, excluding seller concessions), very close to ask, though they took longer to find an offer than a year ago: 70 days year to date, against 64. Loveland and Longmont sit within about three tenths of a month of each other on supply and have since May, so we won't tell you which is 'the tightest' — the order has flipped more often than not and it isn't a fact about either town.
Are Loveland home prices going up or down?+
Flat, on the window that matters. Loveland's single-family median is $528,750 year to date through August 2026 against $530,000 for the same stretch last year, a difference of about a quarter of a percent, which is noise (CAR/IRES). The month figures wander more: $534,500 in August against $539,900 in August 2025. That is what a median does when the mix of what sold moves. A town median tracks the price of what sold, not the value of any one home; for value versus mix, the FHFA repeat-sales indexes for the Fort Collins-Loveland metro, read over a full year, are the honest instrument.
Why is insurance such a big factor in Loveland's move-up market?+
Because the west-side foothills, canyon-mouth, and lakeshore stock a move-up dollar reaches in Loveland carries wildfire and flood exposure, and on those homes insurability (whether you can bind coverage, and at what cost) can decide the deal before price does. It doesn't show up in a median. We cover the parcel-level insurance question in the Loveland market and neighborhood hub.
How often is this report updated?+
Monthly, at this same URL, with a refreshed last-updated date. The figures come from the Colorado Association of REALTORS Local Market Update for Loveland, built on IRES MLS data and published roughly four weeks after month end.
Sources & data notes
- All Loveland, Longmont and Boulder figures: Colorado Association of REALTORS Local Market Update, single-family, sold, August 2026 (and year-to-date through August), stamped current as of September 3, 2026, published free each month by the Loveland-Berthoud Association of REALTORS, built on IRES MLS data. Loveland · Longmont · Boulder. Loveland: median $534,500 (month) / $528,750 YTD, against $530,000 YTD a year earlier; average $600,635 (month) / $610,332 YTD; 72 days (month) / 70 YTD, against 65 / 64 a year earlier; 3.0 months of supply (2.8 in July, 3.9 a year ago); 104 sales in August, 842 year to date; 99.0% of last list price; inventory 310.
- Basis matters. These are single-family figures. Loveland townhome/condo is a separate market; any blended "Loveland median" mixes the two. Medians, averages, and percent-of-list exclude seller concessions.
- "Percent of list price received" (99.0%) is measured against the last list price, after any reductions, not the original. It is not evidence that prices are holding.
- Days on market is an average from listing to accepted offer, not to closing. Months of supply is inventory divided by trailing-twelve-month average pending sales (ShowingTime, which produces the report). ShowingTime's own cut-offs: below 4.0 the market favors sellers, above 6.0 buyers, and "a balanced market will lie somewhere between four and six months of supply." The bands read speed; the median is the price read.
- Single-month figures are noisy (104 Loveland single-family sales in August); we lead with year-to-date.
- Correction (October 2026): a section of this report carried over from the June 2026 release described Loveland as "up about 1.0%" year to date, "the only corridor town still positive", with a table of June figures. That was no longer true from the July release onward; it has been replaced with the August figures above.
- Insurability on Loveland's west-side foothills/lake stock (wildfire + the 2013-remapped Big Thompson floodplain) and the metro-district mill levy on east-side master-planned homes are parcel-level costs a town median cannot show; see the Loveland hub.
- What we do not publish: a months-of-supply or median figure for the $800K–$1.5M band. No public source breaks it out; a direct IRES broker pull is required.
- A repeat-sales index separates value from mix. The FHFA House Price Index publishes two quarterly for the Fort Collins-Loveland metro area (Larimer County), an all-transactions index and an expanded-data index.
Get the monthly Loveland read.
Real MLS numbers, and the basis they're actually measured on, about once a month. Unsubscribe any time; see our privacy policy.
See also: the Loveland market and neighborhood hub · the buy-before-you-sell playbook · bridge loan vs. sale contingency · what a move-up budget buys across the corridor. External: CAR Local Market Update: Loveland (IRES data) · Larimer County Assessor.
Daniel Hsieh is a licensed Colorado real estate broker with True North Boulder, brokered by eXp Realty. Market figures are month-old MLS data and are not a valuation of any specific home; verify any number against current IRES or county data before acting. This report is general market information, not lending, tax, or legal advice. Confirm your specifics with your lender, CPA, or attorney.