Your Employer Buys Your Old House: BVO vs GBO, Colorado
The relocation benefit is not help selling your house. It is an offer to buy it, with a contract of sale and a deed you sign. A guaranteed buyout (GBO) is a floor and a calendar. A buyer value option (BVO) is neither: no appraisal is ordered, and nothing is owed until an outside buyer appears.
The paragraph in your relocation package with a two- or three-letter acronym in it says the company will help you sell your home.
Help is the wrong word for it. In the programs the IRS has examined, nobody is helping you sell anything. A relocation management company is offering to buy your house. That's a real purchase, with a contract of sale, an equity payment and a deed you sign. Your employer pays for the service. The company is the buyer.
Which of two shapes that offer takes decides something you will need before you talk to a lender: whether you reach Colorado holding a date, or holding a listing and no number at all.
True North Boulder is a real-estate team with eXp Realty. We haven't read your relocation policy and can't. These programs are written employer by employer, and the document governing yours is in your own file. What follows is the machinery they are built on, taken from the federal revenue ruling that examined three of them, and the questions to put to your own paperwork. All three of those programs opened with an appraisal-based offer to the employee.
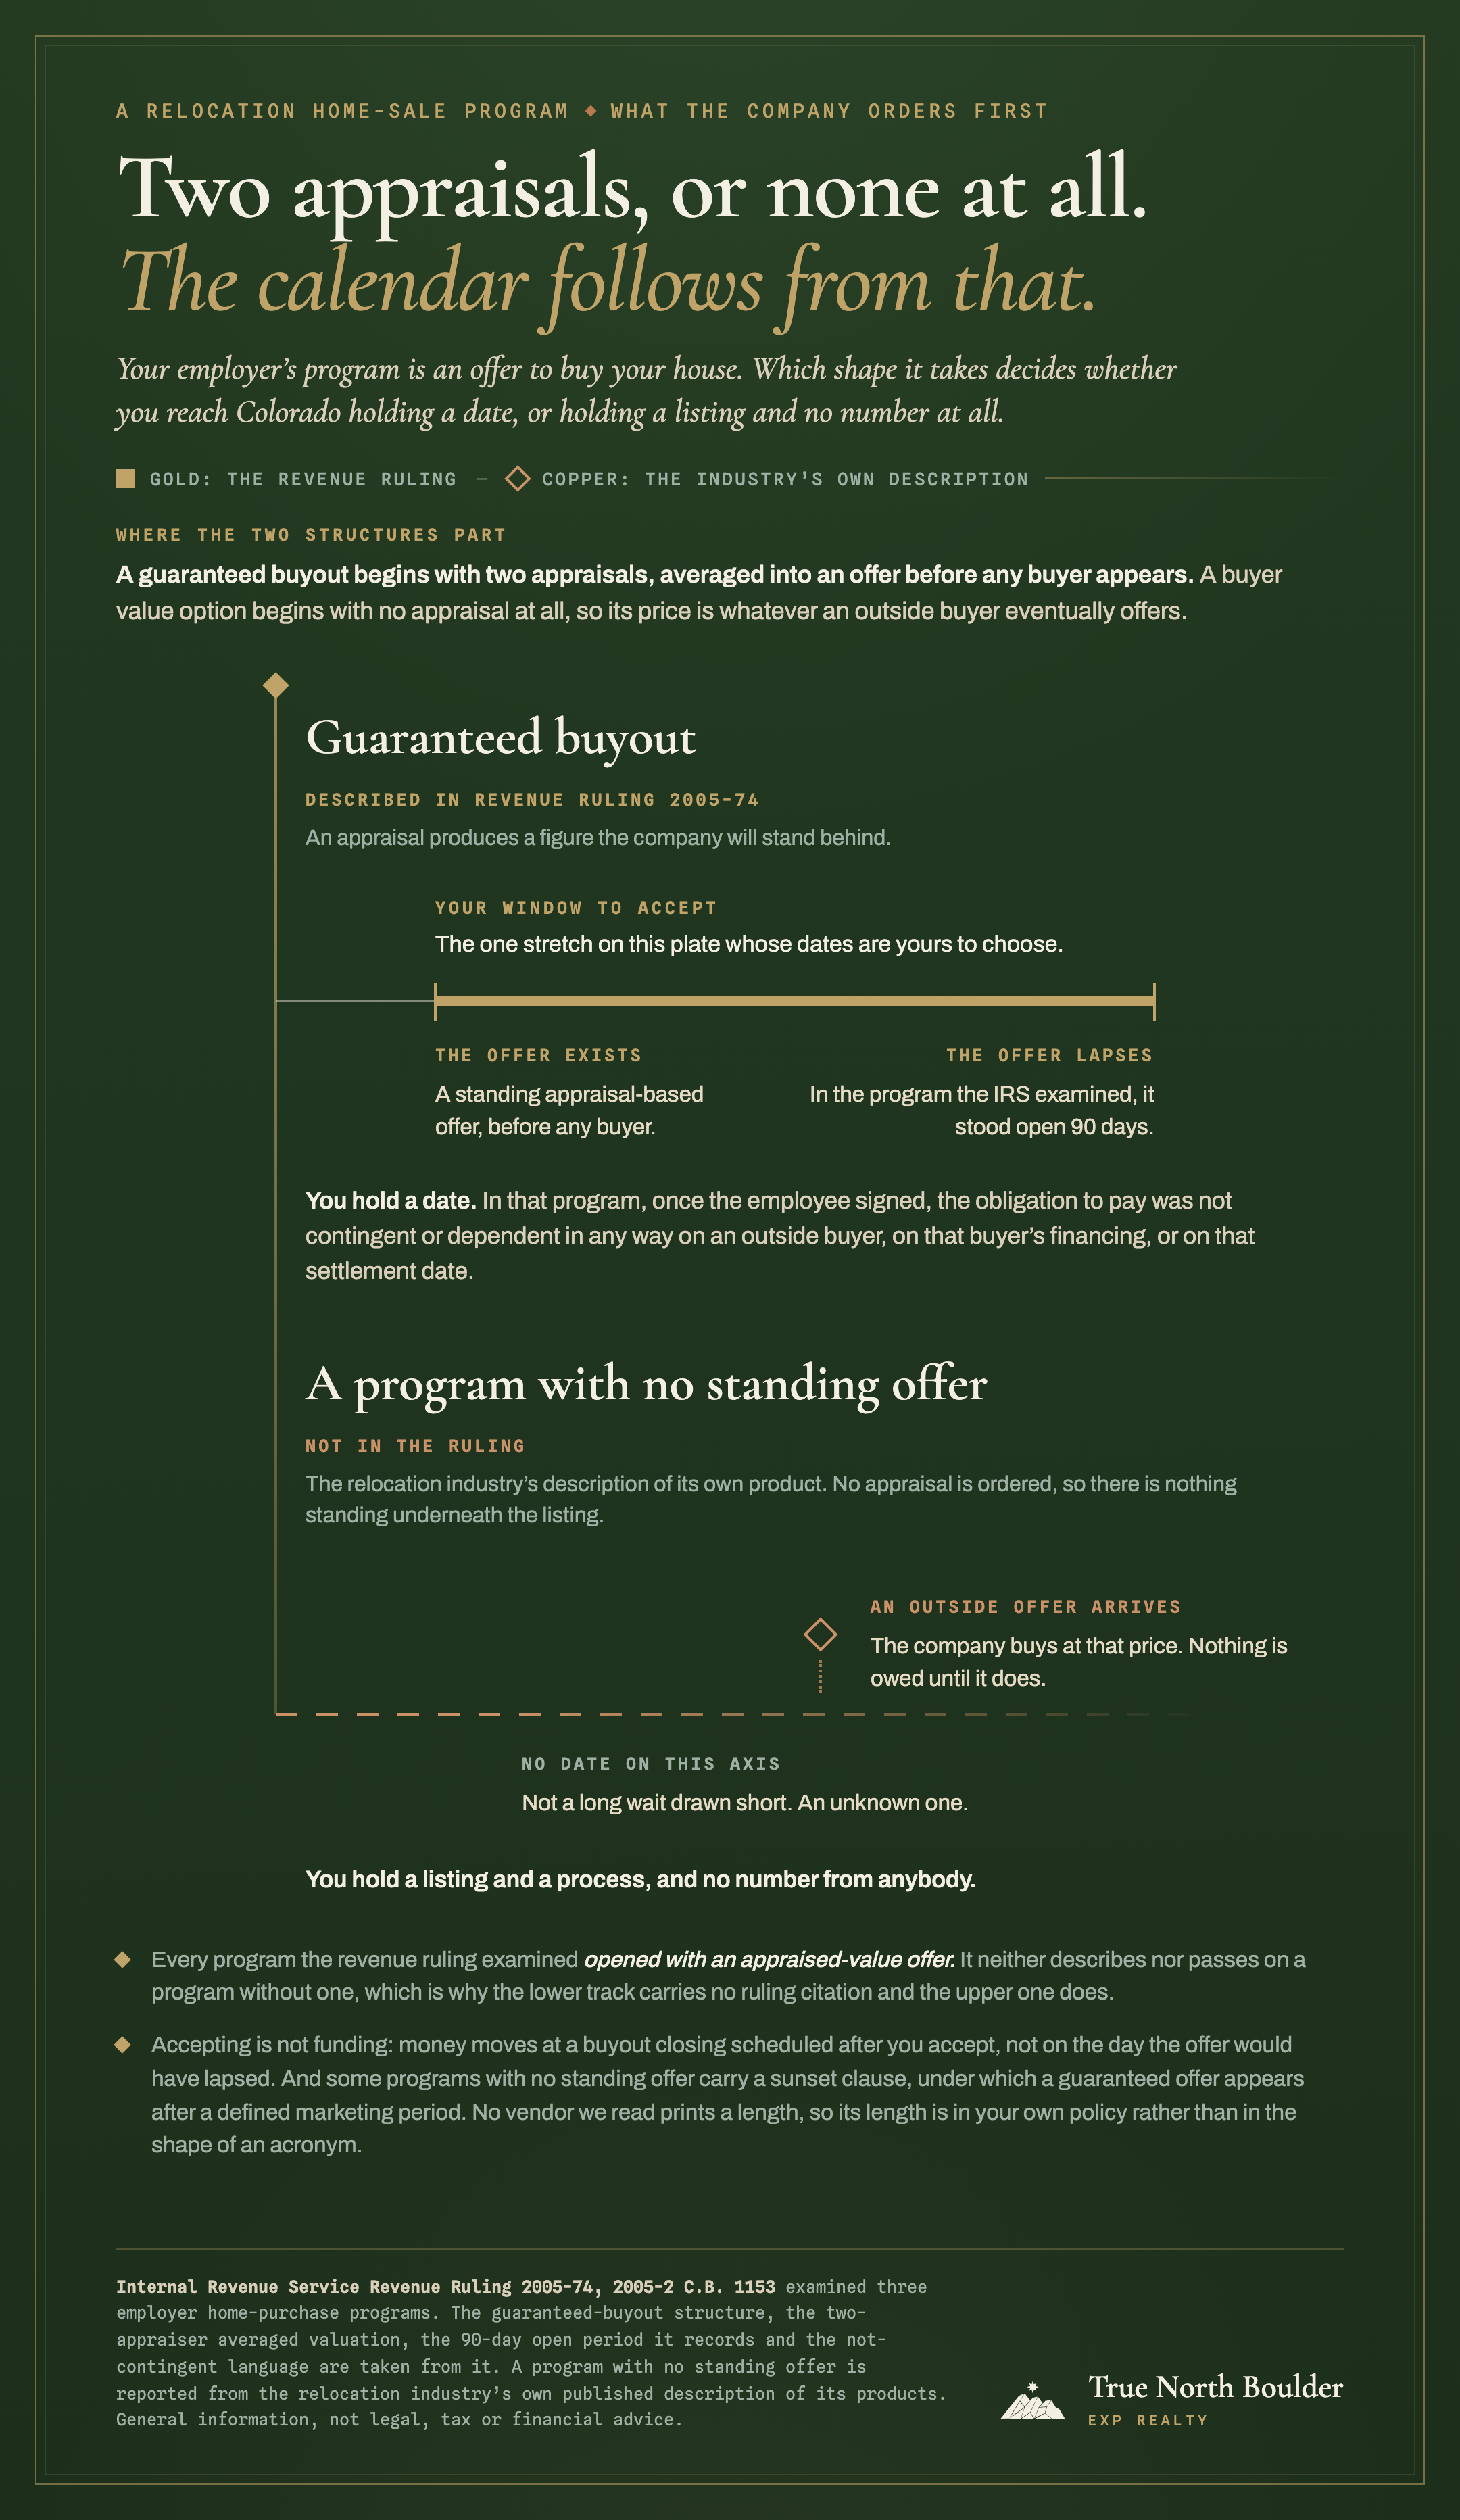
A guaranteed buyout gives you a date. A buyer value option gives you a price.
The two structures end the same way, which is what makes them easy to confuse: the company buys your house and then resells it. They do not start the same way, and the start is the whole of it.
In a guaranteed buyout the relocation company orders two appraisals and averages them, and that average becomes an offer to you before anybody has walked through the house. In a buyer value option it orders nothing. The vendors say so in their own words: one writes that in a BVO home sale scenario, home appraisals are never ordered, another that a buyer value option uses no appraisals and relies entirely on the outside buyer's offer to establish value, a third that the employer does not obtain appraisals or make a formal guaranteed offer to purchase the home. So there is no averaged figure sitting in your file and no offer underneath your listing to be amended upward later. The company's number is your buyer's number, and it arrives once, when the buyer does.
Which makes the fork less a vocabulary question than a question about something that either happened to you or didn't. Did two appraisers come out and value your house? Or did two listing agents give you pricing opinions? Those are different events, and the second one happens in a buyer value option as well: one vendor's own list of what it does for a BVO employee opens with obtain two Broker Price Opinions (Broker Market Analyses). An appraisal produces a figure the company will stand behind. A broker's opinion produces a suggested asking price, and nobody has offered you anything.
A guaranteed buyout (GBO) gives you an appraisal-based offer that exists before any buyer does and stands open for a stated period, and in the program the IRS examined it was not contingent on any outside buyer, so it converts your old house into a date you can write a Colorado offer against. A buyer value option (BVO), as vendors describe it, orders no appraisals at all: there is no appraised figure in your file and no offer standing under your listing until a bona fide outside buyer makes an offer, and nothing is owed to you until one does.
In a guaranteed buyout there is a floor. The appraisal-based offer exists before any buyer does. It stands open for a stated period (in the program Revenue Ruling 2005-74 examined, 90 days), and it is, in that ruling's own description, not contingent or dependent in any way on the company entering a sales agreement with a later third-party buyer, or on that buyer's financing, or on that settlement date. The company is unconditionally obligated to pay the price. Whether anything is marketed underneath that offer depends on which program you have. The amended-value option is the marketing-underneath arrangement: you list the house with a broker chosen from the company's list, and the standing offer sits under your listing as a floor rather than a replacement for it. In the first program the ruling describes there is no such option, and the company lists the house only once it has bought it. Where nothing sells, the company takes the house into inventory.
In a program with no standing offer there is nothing to hold. No appraisals, so no averaged figure, so no offer. Nothing is owed to you until a bona fide outside buyer makes one and the company buys at that price. Until then you hold a listing and a process, and no number from anybody. You do not hold a date.
There is one date this structure can produce, and it's worth going to look for. Some programs carry a sunset clause: where the house hasn't sold after a defined marketing period, a guaranteed offer appears. No vendor we read prints a length, which is why no page can tell you the length of yours. It's in your policy, and for a reader with no standing offer it is the only date on the table.
The amended-value option the ruling describes is a feature that rides on top of a standing offer, not a replacement for one. What the ruling describes is the guaranteed buyout and that amendment. It does not describe a buyer value option at all, and it does not pass on one, which is a reason to read your own document rather than to trust the shape of an acronym.
| What to check | Guaranteed buyout (GBO) | Buyer value option (BVO), as vendors describe it |
|---|---|---|
| How the company's number is set | Two appraisals, averaged, before any buyer appears | The outside buyer's offer. No appraisal is ordered |
| Is there a binding offer if no buyer appears? | Yes. Appraisal-based, open for a stated period | No, unless a sunset clause creates one later |
| What the obligation to pay turns on | Nothing outside it: not on a third-party buyer, their financing, or their settlement date | An outside offer the company accepts as bona fide |
| Who markets the house | The company, once it owns it. Or you, underneath the standing offer, where the program adds an amended-value option | You do, with marketing support from the company, which may also help you choose the agent |
| If nothing sells | The company buys it | You still own it, and the move happened anyway |
| What you can put in a Colorado offer | A date | A price |
One thing to keep separate, because the words collide. This is not the consumer buy-before-you-sell product that iBuyers and bridge lenders sell, and what those programs actually cost is a different page. Those you buy. This one your employer buys, on terms you didn't negotiate and mostly can't.
You sell to the company. Your buyer never becomes your buyer.
Three mechanics sit inside the amendment route the ruling describes, the one that fires when an outside buyer does appear. A fourth is a term of the contract of sale itself, and it applies whether or not any buyer ever turns up. All four come from programs the ruling describes, and those programs carried the standing offer, so treat them as terms to look for in your own paperwork rather than as the signature of one shape or the other. You will not usually find them in the summary HR sent, and each is checkable in a document you either already have or are about to sign.
You do not sign anything with the person buying your house. When a buyer makes an offer, your broker refers it to the relocation company. The company decides whether it is bona fide, amends its contract with you, and then contracts with that buyer in its own name. In the ruling's words, the employee does not sign any contract, binder or other document with a third party buyer, nor does the employee accept any down payment, deposit, or earnest money from one.
Your listing agreement carries a clause that can delete your broker's commission. You select the broker from a list the company maintains, and the listing agreement is required to include an exclusion clause: no commission is earned or due unless a sale to a third-party buyer closes, and a sale of the home to the relocation company terminates the listing with no commission earned or due. Read that from your broker's chair. They're working a file that can end with them paid nothing, through no fault of theirs, by a mechanism written before they took the listing. Then read it from yours, because the clause does something to you as well. Where your listing agreement carries it, the person advising you on whether to take the company's offer is paid only if an outside sale closes, and earns nothing if the buyout does. That's one place in this transaction where your interests and your listing broker's point in different directions, and it's checkable in the clause itself.
Anything above the price is not yours. Where the company resells for more than it paid you, it remits the excess to your employer, and the ruling is flat about the remainder: in no event does any part of that excess reach the employee.
And where the offer is below what you owe, you write the cheque. In the guaranteed-buyout program the ruling describes, if the offer is less than the outstanding balance on the mortgage, the contract of sale requires the employee to pay the difference to the company at or before closing. A benefit can ask for money at a closing table. If your equity is thin, that's the first arithmetic to do, and you can do it this week.
The deed you sign with the grantee left blank
Nothing in an ordinary sale looks like the next document, which is why people remember signing it without quite understanding it.
You execute a deed with the grantee — the space for the buyer's name — left blank. The relocation company then has a choice: insert its own name and record it, or hold the deed and write in the name of whoever eventually buys the house from it.
Nobody walks you through that at the table, and it isn't being hidden from you either. It's how these programs are built, and it's the reason the name on the deed that finally records is yours.
In the programs the ruling describes, it does the second. It does not insert its own name and does not record. When the resale closes it writes that buyer's name into the deed you signed, and that deed is recorded. The consequence, in the words of the reporting-regulation example the ruling walks through, is the part worth keeping: neither Y nor the employer ever becomes a record owner of the residence.
So two things are true at once, and together they are the reason this piece has a second half. In the two programs the ruling treats as a genuine sale to the employer, the company is unambiguously the seller. It holds the property out as its own, deals with lenders, insurers and brokers in its own name, and signs the resale contract as seller. And in that structure it never appears in the chain of title. The person conveying is you.
A note on the disclosure form, and then it gets out of the way, because the page that reads it from the buyer's chair is buying a home from an estate, which works through page one's occupancy block and what a blank row is worth. The inversion is what belongs here. On an estate the knowledge has usually gone with the person who had it. In a buyout it exists one transfer upstream, with the person who lived in the house and then sold it to the company. Whether it travelled is the question.
Which closing is your equity keyed to?
Two dates are candidates, and you control the earlier of them.
The first is the day you sign the contract of sale with the relocation company. The second is the day its buyer closes. Everything that matters to your Colorado calendar follows from which of those your money is tied to.
If it is the signing date, the ruling describes a clean break: nothing related to the company's sale of the home to the third party buyer affects the employee's sale of the home to the company, and where that resale does not close the employee is not obligated under the contract of sale to refund any portion of the purchase price. Your buyer's financing stops being your problem the moment you sign. That's a date you can write an offer against.
Before you sign, it isn't. The industry's own account of a buyer value option is that the employee is funded once the outside contract is deemed valid, and that the fall-through risk sits with the employee. That isn't a contradiction of the ruling; it describes the period before the signature, where the ruling describes the position after it. Both are true of different moments, which is precisely why the signature date is the thing to go and find.
And where the money moves only when the outside buyer closes, you may not be in the transaction you think you are in. In the third program the ruling examined, the company was not obliged to amend its offer until it had a contract with the buyer, the employee kept the right to approve or reject offers, and the higher proceeds reached the employee only if and when the sale to the third party buyer closes. The IRS held that arrangement to be one sale, from the employee straight to the buyer. The gain on the sale stayed the employee's gain; what became taxable compensation were the costs the employer carried on the house along the way, its maintenance, taxes, insurance and losses. Whether your program is written to stay clear of that is a question for a CPA who can read your policy. Take them two documents, your policy and the ruling itself, and ask it in words you can say out loud: does my money move when I sign, or only if my buyer closes? That's the same question an underwriter will ask about the same file, and it's cheaper asked before the move than at filing.
What we are not telling you
We have not read your relocation policy, and no page can. These programs are written employer by employer, and the revenue ruling describes three of them rather than all of them: two it treats as a sale to the employer followed by a separate resale, one it does not. Everything above about how these programs work is either what the IRS examined or what the industry describes as its own ordinary practice, and any of it can be varied in your document. The answers are in your policy and your listing agreement. What a page can give you is which questions decide the Colorado calendar.
What a program with no standing offer does to an offer here
A Colorado offer is a set of dates. The deadlines run on their own, and a seller weighing two offers is largely weighing whose dates look real.
A guaranteed buyout converts your old house into one of those dates: you can commit to a closing date and back it. A program with no standing offer cannot produce that sentence, and no amount of goodwill from your employer will produce it for you.
Whichever shape you have, take it to a lender before you take it to a house. Until your departure mortgage is gone, or a lender can stop counting it, it sits in your ratios and sets the pre-approval letter you shop with, which is a week-one problem rather than a house-hunting one. Bridge loan versus sale contingency puts the trigger in plain terms: a lender stops counting the old payment once you have an executed sale contract with the financing contingencies cleared. A signed guaranteed buyout is that contract, and in the program the IRS examined the obligation to pay under it was not contingent on an outside buyer's financing or settlement date. An unsigned program with no standing offer isn't a contract at all. So the question you were already going to put to your relocation file, whether the obligation to pay is unconditional or keyed to the resale, is the question an underwriter will ask about the same document. Same paper, different desk. And if you are holding a signed buyout, don't write yourself back into a home-sale contingency out of habit: send the executed contract along with your offer, because proof travels with an offer and does nothing sitting in a file.
Being in the no-standing-offer position changes which moves are available rather than leaving you without any. The levers for writing a competitive offer while a sale is still outstanding are all in winning a contingent offer in Boulder: going under contract first, the kick-out, an appraisal gap, a rent-back, and the difference between a home-sale and a home-settlement contingency. The financing comparison is in bridge loan versus sale contingency. This page adds only the upstream fact of which chair you are in when you get there.
A buyout changes the shape of the overlap rather than removing it. The contract of sale in the guaranteed-buyout program the ruling describes requires you to vacate and deliver possession within a set period, but you still own the house until the buyout closes, so the ordinary window is an empty house in your name, which is precisely when a homeowner policy stops behaving the way it did while you lived there — and on the standard form the freezing arm turns on whether the heat stayed on rather than on how long the house sat. Owning two homes during a move is written for that gap, so call your carrier before you hand over the keys. You can also end up owning none of it for a stretch, which is the same window seen from the other end, and it's what the temporary-housing part of your package is for.
The tax side has its own page. Whether the departure house is out of state or you are selling a Colorado house on the way out, Colorado's nonresident withholding on a home sale already carries the point that a buyout puts two transfers on the table and you may not be the transferor on the one that closes. And the origin state still has its own claim on the first of those two closings, which is the one where you are the seller: selling a California home and moving from Texas each work through that half.
When the seller here is a relocation company
This is the second half that section promised, and it is the same transaction with you on the buying side. A relocation company selling a house in this market lists it through a licensed broker on the same MLS as everyone else, and the listing itself is unlikely to say so, which is why you can't screen for it and have to read for it. The title commitment is where it can show. After the section above you know why: where the seller named on the contract is a corporation and the vested owner on the commitment is a private individual, that mismatch is the structure itself. Read the commitment rather than expecting a person, because the company has the option of taking title in its own name and some do. It arrives on a deadline you already have, one of the dates in Colorado's contract deadline schedule, which is early enough for it to matter.
Before you write, establish two things through your broker. Ask who actually signs for the seller and how long a decision takes: approval on that side can run a corporate chain on a business-day cycle, and a customary 24-hour acceptance deadline can expire with nobody having said no. And expect the disclosure to be thin, for the reason the deed section above gives, which is that the seller never lived in the house. That's the same shape the estate-sale guide above works through, and it's worth reading before you set your own dates.
The offer will likely come with an addendum the seller supplies, and that changes what your own broker is permitted to tell you about it. Colorado's rules sort the forms a broker may use into eight categories, and withhold the permission to advise you on a form's effects for exactly two of them: a form supplied by a party to the transaction, and a form prescribed by a government agency or a lender. On those two, a broker's use is limited to inserting transaction-specific information within the form.
The Commission states the consequence outright, in a position statement it revised in August 2026. A broker representing a buyer purchasing from a seller using its own contract forms may help the buyer with the transaction, but is not permitted to advise the buyer regarding the legalities and risks associated with forms and contracts that are not Commission-Approved Forms as set forth in Rule 7.1, and must advise the buyer to seek legal counsel from a licensed attorney before the buyer signs a purchase contract. Our guide to buying new construction walks that rule and that position in full, on the seller class they were written about, which the Commission calls Selling Principals. Whether a relocation company is in that class is a question we can't answer for you. Which of those limits reaches your own broker is a question for them, and the addendum itself is a question for an attorney. Both routes end in the same place regardless.
A second rule produces a document. Where a principal to the transaction requires the use of a purchase contract that the principal created, the Commission's own examples being a homebuilder, a bank-owned seller or an instant buyer, a broker representing a consumer is required to send that consumer a written communication advising them to seek legal advice from a licensed attorney, and to send it before the consumer enters into the contract. Note the trigger: a purchase contract created by the principal, not an addendum riding on the Commission's own contract. Whether it reaches your transaction depends on what the seller is actually asking you to sign, which is worth establishing before you write. A rule that produces a written communication produces something you can keep.
Both routes end in the same instruction: get a lawyer. A broker who won't interpret the addendum for you is following the rule rather than being careful with you.
Two duties are worth knowing about, and they rest on different ground. If the addendum sells the house as-is (read yours rather than assuming), the first is the seller's own: Colorado's disclosure form states on its own first page that the duty to disclose a known adverse material fact is owed whether or not the form carries a line for the item. Whether an as-is clause reaches a duty in that shape is a question for a Colorado real-estate attorney, and the form states the duty rather than the answer. The second is the listing broker's, and there the ground is firmer, because it's statutory. Under Colorado's brokerage statute a seller's agent owes a buyer no duty except that they must disclose to any prospective buyer all adverse material facts actually known to them, subject to a statutory carve-out for psychologically impacted property; a transaction-broker owes an equivalent disclosure to both sides. The broker's duty is imposed by statute rather than by the contract in front of you, so it is not the seller's to write out of it. Neither duty comes from the addendum, which is why a page can state them and your own broker still cannot interpret your addendum for you. And both reach only what is actually known, which on this transaction's own showing is thinner where the seller never lived in the house.
What your file has to show before you make an offer here
Four answers if you are the one selling, and a fifth if you are the one buying here. Most of them are sitting in documents you already have, and where one isn't, it's an email away.
- Which structure you were given. Your relocation policy, and the full document rather than the benefit summary. Ask HR or your mobility team for the policy itself, and where a summary is all you have, treat the question as still open, because the policy is what governs and a summary isn't it. The question to put to it is not which acronym it uses, but whether an offer stands if no outside buyer appears.
- Whether the offer expires, and when. A guaranteed offer stands open for a stated period. Find the period, then put its end date on the same calendar as your Colorado deadlines, because those two clocks have no idea the other exists. Then find the other date: when accepting the offer would actually put money in your account. That one is set when the buyout closing is scheduled, after you accept, and it isn't the day the offer lapses. And if no offer stands, look for a sunset clause, which is the one thing that can put a guaranteed offer in front of you later. Where there's one, the marketing period it runs on is your only real date, so find out how long it is.
- Which closing your equity is keyed to. The day you sign with the relocation company, or the day its buyer closes. Your policy usually answers it and the contract of sale settles it, so start with the policy, which is the one you can read today. If neither says plainly, ask in writing, and ask your employer's HR or mobility team as well as the relocation counsellor. A counsellor runs procedure and sends documents, and works for the counterparty, so the question of when risk passes is one for your employer's side. Emailing the wrong one costs a week, and a week matters on this clock.
- Whether the listing agreement carries the exclusion clause. Your listing agreement, before you sign it. It decides what your broker is paid and when, and along with the contract of sale it's one of the two documents on this list you sign rather than merely read.
- And if you are the buyer here, what the seller is asking you to sign. An addendum riding on Colorado's own contract is one thing. A purchase contract the seller wrote itself is another, and that one obliges your broker to send you a written communication telling you to seek legal advice before you sign. Ask which you are being handed, and keep whatever comes back.
Answer the third and you have made the decision the wider relocation guide organises everything else around: whether you house-hunt here as a buyer with funds or as a buyer with a condition attached. Relocating to Boulder County runs the order from there — employer, then node, then town, then parcel — and where it says the timing of your origin-home sale matters, this is the page it meant.
This is general information about federal tax guidance, Colorado's brokerage statute and the Real Estate Commission's rules and approved forms. It is not legal, tax or financial advice, and it is not an opinion about your relocation policy, which we have not seen. What your program does, and what it costs you, are questions for your own policy document, your relocation counsellor, a CPA, and, on the addendum, a Colorado real-estate attorney.
Once you can answer the third question, we can tell you what it buys you here.
Which closing your equity is keyed to decides what a Boulder-area seller will take from you: which deadlines you can realistically agree to, whether an offer reads as funded or conditional, and whether the levers in the contingent-offer guide are yours to use. If you are on the other side of it and the seller is a relocation company, our half of that file is the part Colorado lets a broker do: the title commitment, the disclosure, the deadlines, and finding out who actually signs for the seller and how long their side takes to answer. The addendum goes to a Colorado real-estate attorney before you sign it, and we will say so rather than talk you through it. If what you are handed turns out to be the seller's own purchase contract instead, the written communication telling you to get that advice is ours to send you.
Daniel Hsieh is a licensed Colorado real estate broker with True North Boulder, brokered by eXp Realty.
Frequently asked
What is the difference between a BVO and a guaranteed buyout?+
Whether an offer is already standing if no outside buyer appears, and the two do not run on the same machinery underneath that. In a guaranteed buyout the relocation company orders two appraisals and averages them, and that average is an offer: it exists before any buyer does, stands open for a stated period, and in the program the IRS examined it was not contingent or dependent in any way on the company entering a sales agreement with a third-party buyer, on that buyer's financing, or on that settlement date. In a buyer value option, relocation companies are consistent in describing their own product: no appraisals are ordered at all. The price is whatever a bona fide outside buyer offers, so until one arrives there is no appraised figure anywhere in your file and no offer standing under your listing, and nothing is owed to you. Here is a test you can run on your own memory: did two appraisers come out and value the house, or did two listing agents give you pricing opinions? Those aren't the same event, and the second one happens in a buyer value option too. Every program the revenue ruling examined opened with an appraised-value offer, so the appraisal-free version is the industry's account of its own product rather than the IRS's. Programs are written employer by employer, so read yours rather than the acronym.
Do I sign a contract with the person buying my house?+
In the amended-value structure, meaning a guaranteed buyout you are allowed to market underneath, no, and that's the part that surprises people. Your broker refers the outside offer to the relocation company. The company decides whether it is bona fide, amends its own contract of sale with you to match the price, and then contracts with that buyer in its own name. The IRS put it directly in describing these programs: the employee does not sign any contract, binder or other document with a third-party buyer, and does not accept any down payment, deposit or earnest money from one. You sell to the company. The person who moves in is the company's buyer, not yours.
What happens if my buyer's loan falls through after I have been paid?+
It depends entirely on when you signed, which is why that date is the one to find. In the programs the IRS examined, once the employee has signed the contract of sale, nothing related to the company's later sale to a third-party buyer affects the employee's completed sale to the company, and if that resale does not close the employee is not obligated to refund any part of the purchase price. Before the signature the position is different, and the industry's own description of a buyer value option is that funding follows the outside contract being deemed valid and that the fall-through risk sits with the employee until then. Both descriptions are true of different moments. Ask in writing which date your equity is keyed to, and ask your employer's HR or mobility team as well as the relocation counsellor, because policy interpretation usually sits on the employer's side. Keep the answer, because you'll be asked for it twice: once by a lender, and once by whoever prepares your return.
Can my agent explain the relocation company's addendum to me?+
Not in the way you probably want, and the limit is a rule rather than a preference. Start from your own side of it. The Commission's position statement says that a broker representing a buyer purchasing from a seller using its own contract forms may help the buyer with the transaction but is not permitted to advise the buyer regarding the legalities and risks associated with forms and contracts that are not Commission-Approved Forms as set forth in Rule 7.1. The same statement also says brokers must advise the buyer to seek legal counsel from a licensed attorney before the buyer signs a purchase contract. Both of those sentences are written about brokers dealing with the sellers that statement calls Selling Principals, and we make no claim that a relocation company is one. The reason sits upstream, in how Colorado sorts the forms a broker may use at all: there are eight categories, and six of the eight expressly state that the broker may advise the parties as to the effects thereof, while the two that do not, a form supplied by a party to the transaction and a form prescribed by a government agency or lender, each limit the broker's use to inserting transaction-specific information. Which of those limits reaches your own broker is a question for them, but on either route a broker who declines to interpret the addendum is following a rule rather than dodging your question.
Sources & data notes
- The two structures, and every mechanic attributed to "the ruling". IRS Revenue Ruling 2005-74, 2005-2 C.B. 1153, read from the PDF published at irs.gov, pages 1 to 14. Quoted or reported here: the averaged two-appraiser offer, the 90-day open period, the not-contingent-or-dependent language and the unconditional obligation to pay (Situation 1); the vacate-and-deliver-possession term and the requirement to pay the difference where the offer is below the mortgage balance (Situation 1); the broker-from-the-company's-list requirement, the listing-agreement exclusion clause, the no-contract-and-no-earnest-money-with-the-third-party-buyer term, the amendment to match a bona fide higher offer, the no-refund-if-the-resale-fails term, and the excess remitted to the employer (Situation 2); the blank deed and the record-owner consequence (Situations 1 and 2); and the one-sale holding, in which the employee realises the gain on the sale while the costs the employer carried on the home, its maintenance, taxes, insurance and losses, are taxable compensation to the employee under section 61(a)(1) (Situation 3). All three situations in the ruling open with an appraised-value offer to the employee, and the ruling neither describes nor passes on a program with no such offer under it; where this piece describes that shape it is reporting the relocation industry's account of its own product, labelled as such on the page.
- The 90 days is a fact of the program the IRS examined, in a 2005 ruling — not a rule and not an industry standard. It is reported here scoped that way every time it appears, and it appears nowhere in the FAQ unscoped. Your own offer period is in your own policy.
- The form categories. Colorado Real Estate Commission Rule 7.1, Standard Forms, 4 CCR 725-1, read in the 2026 Colorado Real Estate Manual, chapter 2. Counted by us across all eight categories: the sentence "The Broker may advise the parties as to the effects thereof" appears in six of them and is absent from two, Client Form and Government/Lender Form, each of which instead reads that "A Broker's use of such form is limited to inserting transaction-specific information within the form."
- The written-communication rule. Colorado Real Estate Commission Rule 7.5, Non-Commission Approved Contracts to Buy and Sell, 4 CCR 725-1, read at page 59 of the official Code of Colorado Regulations PDF published by the Colorado Secretary of State (served 200 to an ordinary automated fetch; banked in this bundle). Reported here for its trigger, a principal to the transaction requiring the use of a purchase contract the principal created, and its consequence, a written communication advising the consumer to seek legal advice from a licensed attorney before the consumer enters into that contract. It is stated conditionally on the page because that trigger is a purchase contract, not an addendum to a Commission-approved contract, and we make no claim about which of those any relocation company uses.
- What a buyer's broker may say. Commission Position CP-1, Contracts provided by Principals Selling Real Property, recodified August 2, 2022 and revised August 4, 2026, read in the standalone position statement PDF published at dre.colorado.gov (retrieved with a browser user agent, 2026-09-19) and banked in this bundle. Quoted here from its Broker Representing Buyer paragraph, which reads that brokers must advise the buyer to seek legal counsel from a licensed attorney before the buyer signs a purchase contract. The 2026 Colorado Real Estate Manual's chapter 3 reproduction of the same position still reads should, and it differs on the trigger as well as the modal: there the duty arises if the buyer has questions or concerns, where the revised standalone requires it before the buyer signs a purchase contract. The two Commission-published surfaces disagree, and the more recently revised standalone governs. We disclose the discrepancy rather than citing only the surface that suits the claim. We deliberately make no claim about whether a relocation company is a "Selling Principal" under that position, because that class keys to the exemptions in C.R.S. 12-10-201(6)(b) and we could not establish that any of them reaches a corporation engaged in land transactions reselling previously occupied dwellings. Rule 7.1's categories turn on the FORM rather than on the seller's licence status, which is why the mechanism above is stated from the rule. We stop short of saying the rule supplies a fallback that reaches this reader's own broker. Rule 7.1.C defines a Client Form as one provided by a party to the transaction if the Broker is acting in the transaction as either a Single Agent or Transaction-Broker for the party providing the form, and its retention duty runs to that same broker — so on the rule's face the category describes the supplying party's broker, and whether it reaches a buyer's broker is not settled by the text we read. That is a question for the reader's own broker and, on the addendum, for an attorney, which is what the page now says. Rule 7.5's own examples of a principal using its own contract are a homebuilder, a bank-owned seller and an instant buyer, and a relocation company is not named there either, which is consistent with that refusal rather than against it.
- The two duties, and what each rests on. The broker-side duty is statutory: C.R.S. 12-10-404(3)(a), the seller's-agent exception requiring disclosure of adverse material facts actually known to the broker, whose carve-out for psychologically impacted property sits in that same subsection and cross-refers to C.R.S. 38-35.5-101; and C.R.S. 12-10-407(2)(b)(VI) and (VII), the transaction-broker's equivalent duties to the buyer and to the seller respectively. Both read in the 2026 Colorado Real Estate Manual, chapter 1. The seller-side duty is quoted from the header of Commission form SPD19, Seller's Property Disclosure (Residential), adopted August 5, 2025, mandatory January 1, 2026. What that form does not say is whether an as-is clause reaches the duty it states, which is why the page puts that question to an attorney rather than answering it.
- Retrieval note. dre.colorado.gov returns 403 to a plain automated fetch and HTTP 200 to a browser user-agent; all three manual chapters and the standalone CP-1 PDF were obtained the second way, and that PDF is banked in this bundle. The irs.gov PDF failed to parse on fetch and was read as page images from the saved file.
- Industry practice, used only where labelled as such. Three relocation management companies' published descriptions of their own programs, each retrieved 2026-09-19 with a browser user agent and banked in this bundle: WHR Global, ARC Relocation and CapRelo. They appear here because their own published pages are the primary source for how the industry describes its products. They are cited, not chosen: no vendor is named anywhere in the body of this page, none is linked, and the page routes no reader to any of them. We have no business relationship, referral arrangement or network affiliation with any of the three, and we are paid nothing in connection with naming them. Used for four things. First, that a buyer value option orders no appraisals. WHR writes that in a BVO home sale scenario, home appraisals are never ordered, ARC that a buyer value option uses no appraisals and relies entirely on the outside buyer's offer to establish value, and CapRelo that the employer does not obtain appraisals or make a formal guaranteed offer to purchase the home. Three vendors, independently, with no dissent found. Second, that the valuation work in a buyer value option is two broker price opinions rather than appraisals, from WHR's own list of what it provides a BVO employee, which opens Obtain two Broker Price Opinions (Broker Market Analyses). Third, that funding in a buyer value option follows the outside contract being deemed valid and that the fall-through risk sits with the employee until then, and that in a guaranteed buyout the employer takes the home into inventory where the employee cannot sell it, both WHR. Fourth, the sunset clause, from CapRelo, which writes that a Sunset Clause can provide a Guaranteed Offer if the property does not sell after a defined marketing period; none of the three names a period and WHR does not mention the mechanism at all, so this page prints no figure and sends the reader to their own policy. Vendor material is the industry describing itself and is not used for any legal claim. Where it appears to conflict with the ruling, the conflict is resolved by scope rather than by choosing: the ruling states the position after the employee signs the contract of sale, the vendor describes practice before that signature, and the draft states both moments.
- What is deliberately not here. We have not read any particular relocation company's addendum and make no statement about one. No commute, node, neighbourhood or school material appears in this piece; that is the wider relocation guide's, and linking to it is the whole of what we do with it here.


