Boulder Home Prices and Housing Market Report (Updated Monthly)
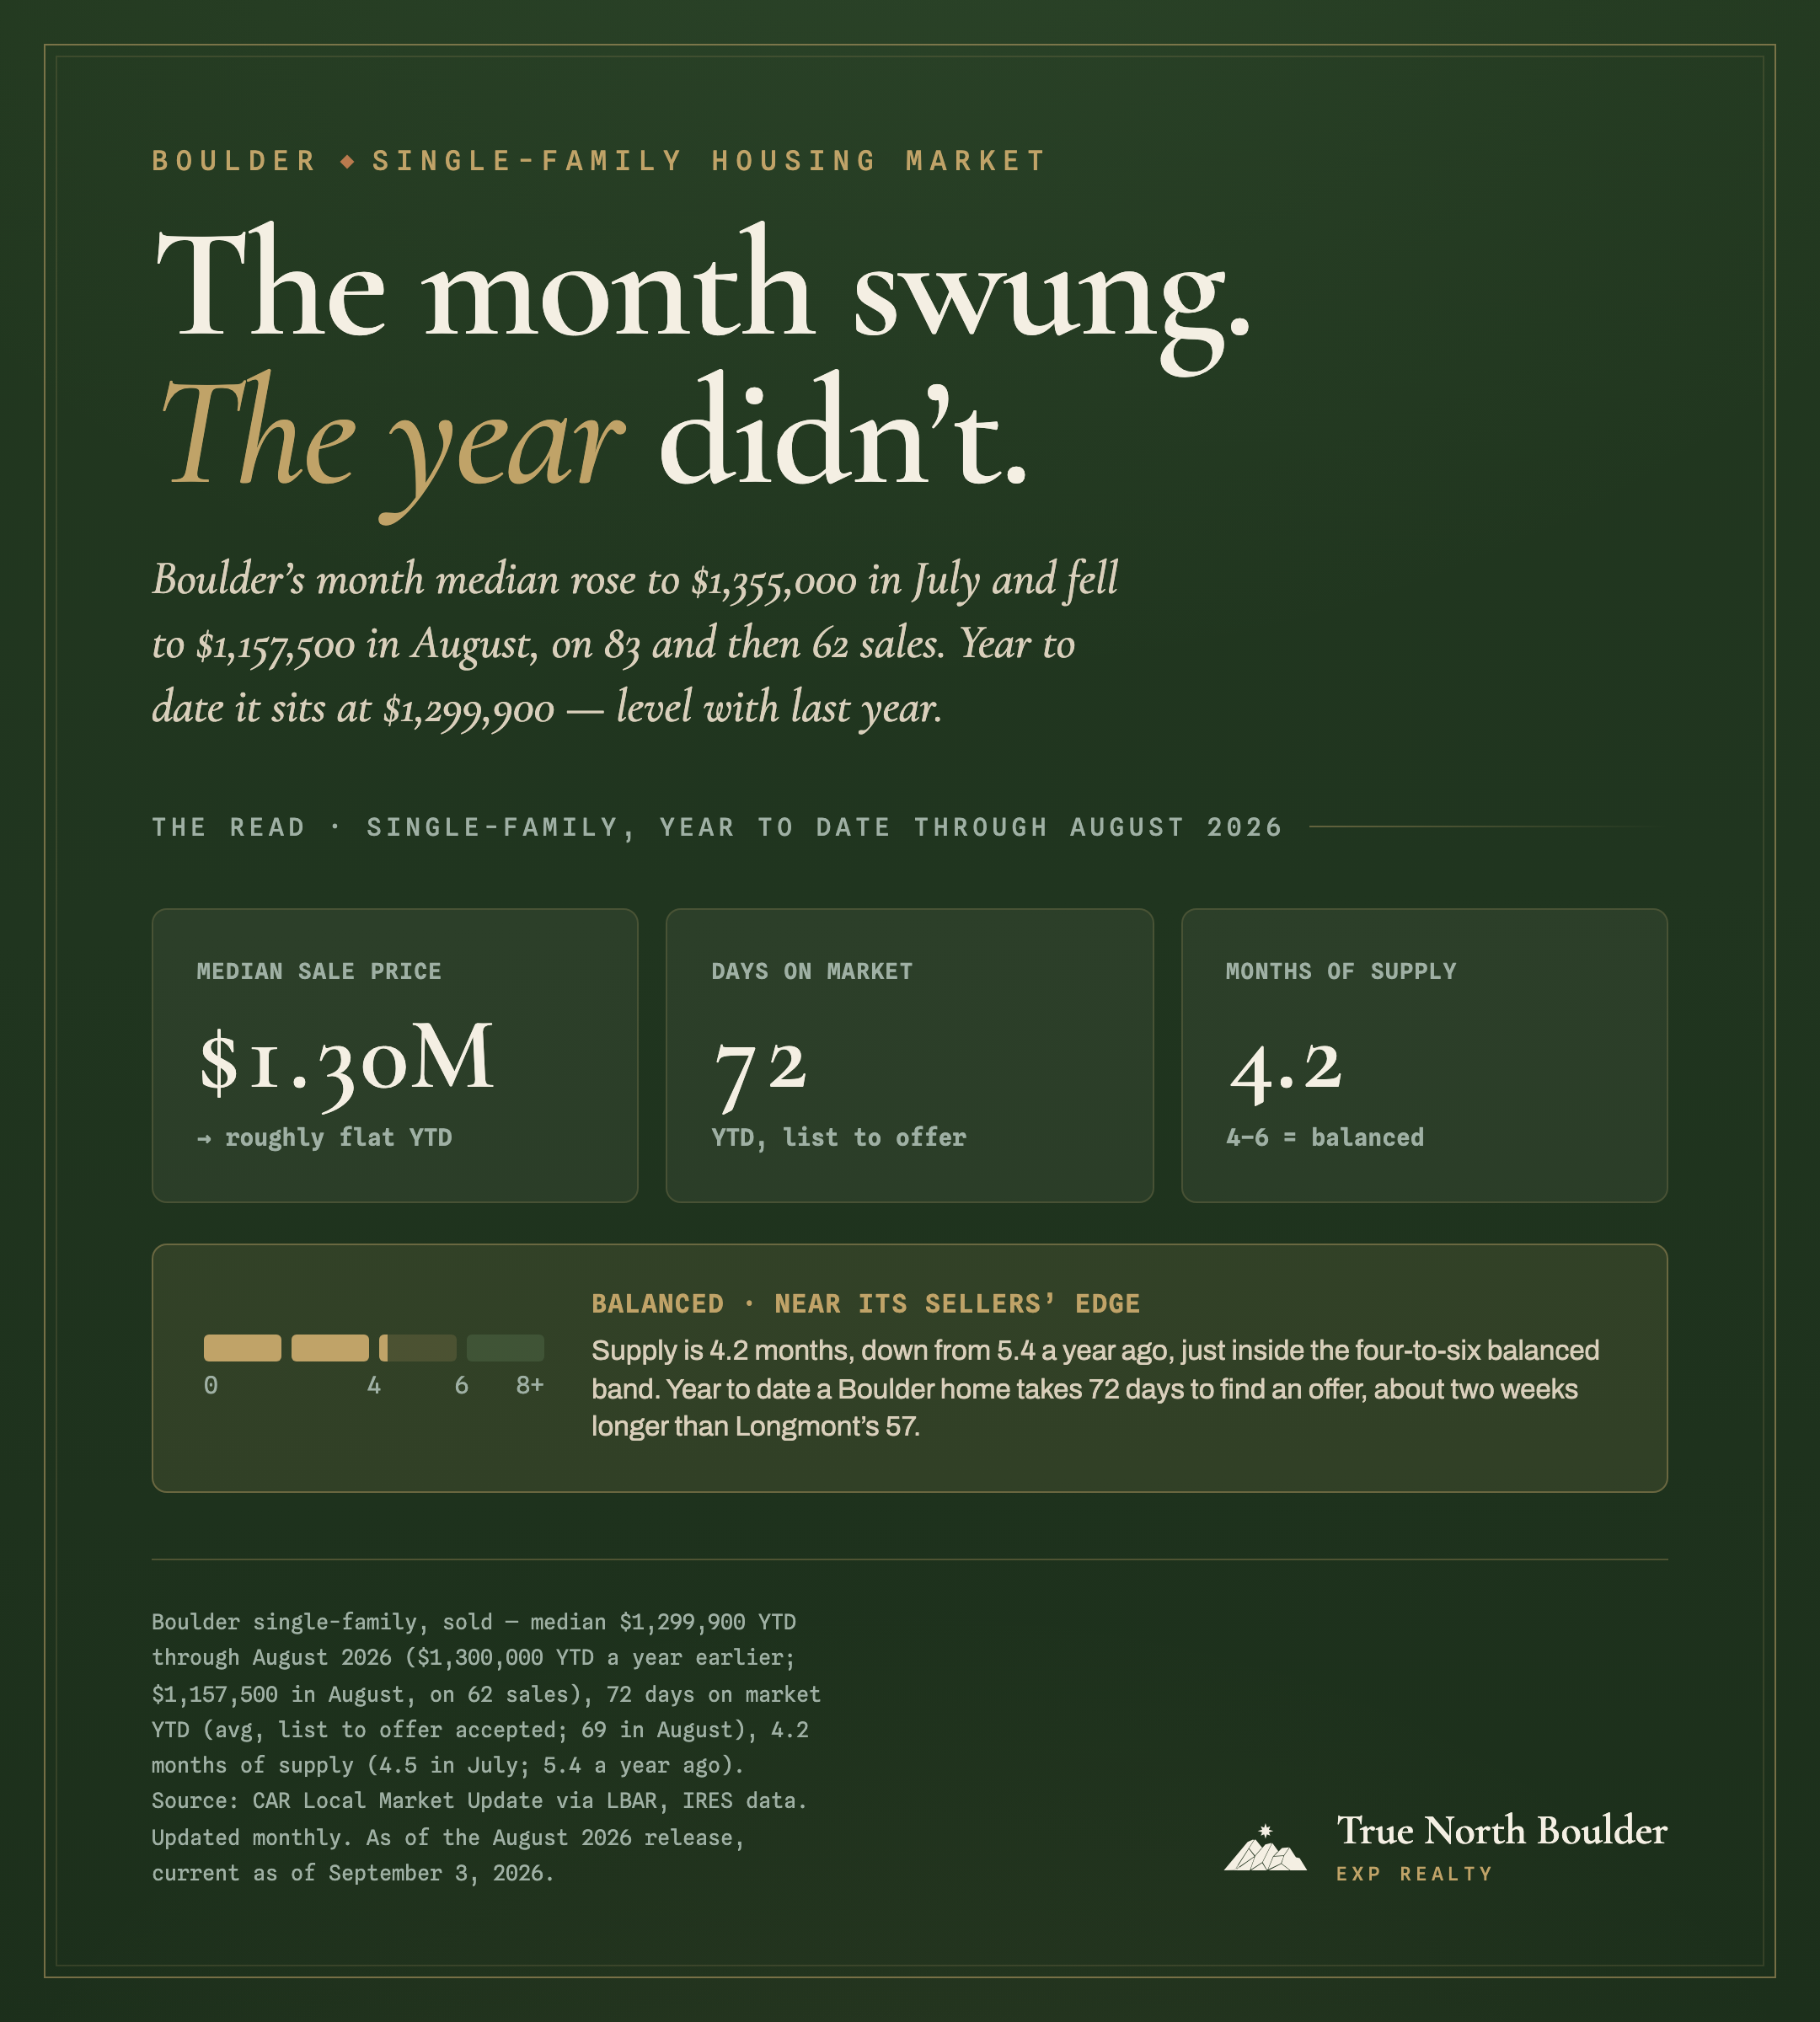
Boulder's single-family median is $1,299,900 year to date through August, level with last year, even though the month figure swung from $1,355,000 in July to $1,157,500 in August. Supply is 4.2 months. That median isn't your price: the move-up band straddles it.
Last updated: October 2026. Figures are single-family sold data for the city of Boulder, from the Colorado Association of REALTORS Local Market Update (data from IRES, the Front Range MLS): the latest release is August 2026, stamped current as of September 3 (the September update is expected in late October).
Boulder's single-family median was $1,299,900 year to date through August 2026, level with last year, while supply sat at 4.2 months and the average home took 72 days to find an offer (CAR/IRES). The month figures tell a noisier story than that. The month median rose to $1,355,000 in July and fell to $1,157,500 in August, on 83 and then 62 closings, and days on market went from 87 to 69 in the same two releases. Neither swing is a trend. The year-to-date line barely moved through both. Two things follow that most coverage skips. First, that median is the middle of the whole town, and the $800K–$1.5M move-up band straddles it, with the top in the luxury tail above. Second, "roughly flat year to date" is a statement about the price of what sold, not about what your house is worth. This report is about the gap between the town number and your number.
What's the Boulder median right now?
Boulder single-family closed at a median of $1,299,900 year to date through August 2026, against $1,300,000 for the same stretch last year. Hold that figure, not the month. August rests on just 62 sales, down from 83 in July and 112 in June, and on a $1.3M market a handful of high-end or entry closings move the median by six figures: July's month median was $1,355,000, August's is $1,157,500, and the year-to-date line moved by $100 across both. That is exactly the month-noise the year-to-date read is there to smooth. The average shows how skewed the year is: $1,642,526 year to date against the $1,299,900 median, a gap of about 26%, which is the signature of a long luxury tail pulling the top.
Read those figures the way we compile them: single-family, sold, city of Boulder. And note the one number we deliberately won't publish.
The town median is not your price
Every figure here is single-family, sold, for the city of Boulder, from the Colorado Association of REALTORS Local Market Update, built on IRES MLS data and published free each month. Medians, averages and percent-of-list all exclude seller concessions.
We won't publish a months-of-supply or median figure for the $800K–$1.5M band. Half of Boulder's single-family sales close above the median, so the move-up band straddles it: much of it clears at or below that line, with real competition, while the top of the band sits in the slower, choosier luxury tail above. No public source breaks the band out; it takes a direct IRES pull. If you're transacting in that band, ask us to pull yours, so you're weighing a comp set for your own house instead of a town average that was never about you.
Did the Boulder median really drop almost $200,000 in a month?
It didn't, in any sense that matters to your house. The month median is the middle of whatever happened to close that month, and August closed 62 single-family homes, the fewest since February. July's 83 closings skewed expensive and printed $1,355,000; August's 62 skewed toward the middle and printed $1,157,500. Days on market did the same dance, 87 in July and 69 in August. Read on their own, those two months tell you Boulder got pricier and slower, then cheaper and faster. Neither is true. Across all 595 sales this year, the median is $1,299,900, the average wait is 72 days, and both are close to where they were a year ago.
The number that did move is supply: 4.2 months in August, down from 4.5 in July and 5.4 a year ago. The shelf is getting a little shorter. The price of what sells off it has not moved.
So here's the line we hold. What's essentially flat year to date is the price of what sold. That is not the same as saying your house is worth exactly what it was, and a $1,157,500 month figure is not the same as saying it went down. A town median can't separate a change in value from a change in what happened to trade. The instrument that can is a repeat-sales index, which follows the same homes selling twice; the FHFA publishes two quarterly for the Boulder metro area (Boulder County), and because they can disagree in a single quarter, read them over a full year for value rather than mix.
One structural fact sits under all of this and makes Boulder different from the corridor towns. Boulder adds almost no net-new single-family homes. The city issues permits every year, but construction here is largely scrape-and-replace: a teardown becomes a larger house on the same lot, and the home count barely moves. So the supply that sets price is the existing shelf changing hands, not new building. That's why months of supply, not permit counts, is the number that matters in Boulder, and it's the deeper reason the shelf can hold steady while the median wanders. We unpack what that does to a move-up trade in the Boulder market and neighborhood hub.
Is Boulder a buyer's or a seller's market?
Balanced, near its sellers' edge, and looser than the corridor towns below it. Boulder single-family supply is 4.2 months, down from 4.5 in July and 5.4 a year ago. ShowingTime, the company that produces the CAR reports, treats four to six months as balanced, with sellers favored below that band and buyers above it. Boulder is inside the band, and over the past year it has drifted toward the four-month edge; we cover what a balanced reading does and doesn't tell you separately. What surprises people is the direction of the comparison: Boulder is the looser market, by about 1.2 to 1.4 months, and Longmont and Loveland are the tighter ones.
The clock says the same thing more gently than July suggested. Year to date, a Boulder home takes 72 days to go under contract; a Longmont home takes 57. That two-week gap was 11 days a year ago. The month figures briefly showed a 44-day gap in July (87 days against 43), and August's show 17 (69 against 52, about where it was a year ago), which is why we read the year to date and not any single month.
| Single-family | Boulder | Longmont | Loveland |
|---|---|---|---|
| Median, year to date through August 2026 | $1,299,900 | $610,000 | $528,750 |
| Days on market, year to date | 72 | 57 | 70 |
| Months of supply, August 2026 | 4.2 | 2.8 | 3.0 |
| Median, August 2026 (month) | $1,157,500 | $604,000 | $534,500 |
Colorado Association of REALTORS Local Market Updates. Data from IRES, single-family, sold, August 2026 and year to date through August 2026. Town-level figures, not band-level. Longmont and Loveland sit within 0.3 months of each other on supply and have since May; that is one cluster, not a ranking.
For a move-up buyer, that has a real consequence. The classic corridor trade (sell in Boulder, buy in Longmont or Loveland) still means selling into the looser market and buying into the tighter one, the harder direction. If you're buying in Boulder, though, you have more room than the corridor: at 4.2 months and 72 days to an offer, you generally have more time to keep inspection and appraisal protections in an offer than in Longmont, where homes find a buyer about two weeks sooner. What to pay is a separate question, and the level year-to-date median answers it. The Boulder vs. Longmont comparison works that trade in detail.
What should move-up buyers and sellers do?
Settle the money before the sign goes in the yard. If you're trading up out of Boulder into the corridor, you're selling into the softer market and buying into the tighter one, so a home-sale contingency rarely wins the home you want. Plan to write non-contingent, which means the funds exist before you write. If a HELOC is part of that plan, open it before you list; lenders generally won't originate a home-equity line on a home that's already on the market. We walk the financing paths in bridge loan vs. sale contingency and the sequencing in the buy-before-you-sell playbook.
If you're the Boulder seller, the number that should concern you isn't the median, it's the calendar and the tier. At 4.2 months your home will very likely sell — but the average this year has been 72 days from listing to an accepted offer, and that is before closing. Budget the wait. The luxury tail above the median moves slowest and choosiest, while sensibly-priced homes below it can still draw competition. Price and prep to your tier, and if you're trading up, remember the softness on your sell side and the tightness on your buy side are the same problem. And whatever you're told, nobody can tell you whether this is the bottom; anyone who says so is guessing with your money.
The honest take
The Boulder number everyone quotes (a $1.3 million median, essentially flat year to date, with month prints that swung from $1,355,000 in July to $1,157,500 in August) is doing less work than it looks like it's doing. It's a town-wide, single-family, price-of-what-sold figure, and you are not buying the town. The move-up band straddles it, and the luxury tail above behaves nothing like the middle. What's actually true and useful is smaller and more boring: Boulder clears in about four months of supply, a little faster than last month, faster than a year ago, and slower than Longmont and Loveland, while a house here waits about two weeks longer for an offer than one in Longmont. A buyer here still has leverage a Longmont buyer has lost, and a seller here still has to justify a price the market no longer hands over, on a longer clock than the headline median suggests. Price to your tier, finance the trade before you list, and treat the headline median as weather, not a valuation. That read shifts month to month, which is why we re-pull it from the CAR/IRES release every month instead of leaning on a quarterly snapshot.
We won't publish a band number. We will build your comp set.
A comp set at your price and your product, not a town average. That is a CMA, and it's the honest answer to what your Boulder home is worth.
Frequently asked
What is the median home price in Boulder?+
Boulder's single-family median sale price was $1,299,900 year to date through August 2026, essentially level with $1,300,000 for the same stretch last year (Colorado Association of REALTORS Local Market Update, data from IRES). Hold the year-to-date figure, not the month: the August month median was $1,157,500 on only 62 sales, after $1,355,000 in July on 83, and on a $1.3M market that few closings move a median by six figures. That is the single-family figure. Boulder townhomes and condos are a separate market, with a median of $517,000 year to date. For a move-up buyer, the important point is that the $800K–$1.5M band straddles the single-family median: much of it sits at or below it, with the upper end in the luxury tail above.
Is Boulder a buyer's or a seller's market?+
Balanced, though only just. Boulder single-family carries 4.2 months of supply in August 2026, down from 4.5 in July and 5.4 a year ago (CAR/IRES). ShowingTime, which produces these reports, puts a balanced market between four and six months, so 4.2 sits inside that range near its lower edge, while Longmont and Loveland, at 2.8 and 3.0, sit below four, on the sellers' side. A move-up buyer generally has more room to keep inspection and appraisal protections in an offer here than in Longmont, because Boulder homes take longer to find a buyer: 72 days to an accepted offer year to date, against 57. What a home is worth is a separate read, off the solds.
Are Boulder home prices falling?+
No, and they are not clearly rising either. Boulder's single-family median is flat year to date, at $1,299,900 against $1,300,000 for the same stretch last year (CAR/IRES, August 2026). The month figures have swung hard in both directions, up to $1,355,000 in July and down to $1,157,500 in August, but each rests on fewer than 100 sales. A town median measures the price of what sold, which moves when the mix of what traded moves, not only when values change. For whether values are actually rising or falling, the honest instrument is a repeat-sales index; the FHFA publishes two quarterly for the Boulder metro area (Boulder County), and because they can disagree in a single quarter, read them over a full year.
Does Boulder build enough new homes to loosen prices?+
Effectively no. Boulder issues building permits every year but adds close to zero net-new single-family homes, because construction here is largely scrape-and-replace: a teardown becomes a bigger house on the same lot, and the home count barely moves. So the supply that matters for price is the existing shelf changing hands, not new construction, which is why 'months of supply' (how fast that shelf clears) is the number to watch here.
How often is this report updated?+
Monthly, at this same URL, with a refreshed last-updated date. The figures come from the Colorado Association of REALTORS Local Market Update for Boulder, built on IRES MLS data and published roughly four to five weeks after month end — the August 2026 report is stamped current as of September 3, 2026.
Sources & data notes
- All Boulder, Longmont and Loveland figures: Colorado Association of REALTORS Local Market Update, single-family, sold, August 2026 (and year-to-date through August), stamped current as of September 3, 2026, published free each month via the Loveland-Berthoud Association of REALTORS, built on IRES MLS data. Boulder · Longmont · Loveland. Boulder: median $1,157,500 (month) / $1,299,900 YTD ($1,300,000 YTD a year earlier); average $1,555,989 (month) / $1,642,526 YTD; 69 days (month) / 72 YTD; 4.2 months of supply (4.5 in July, 5.4 a year ago); 62 sales in August, 595 year to date; 97.5% of last list price.
- Basis matters. These are single-family figures. Boulder townhome/condo is a separate market (median $517,000 year to date through August; $375,000 on 25 August sales) and any blended "Boulder median" mixes the two. Medians, averages, and percent-of-list all exclude seller concessions — the asterisk on the report attaches to all three, not just the percentage.
- "Percent of list price received" is measured against the last list price, after any reductions, not the original — and the CAR report does not publish an original-list companion, so there is no way to bound the reduction phase from this source. A home listed at $1.4M, cut to $1.3M and sold at $1,269,000 records the same 97.6% as one that never cut. It is not evidence that prices are holding.
- Days on market is an average from listing to accepted offer, not to closing. Months of supply is inventory divided by trailing-twelve-month average pending sales (ShowingTime, which generates the report). The same page reads a balanced market as one that "will lie somewhere between four and six months of supply", with the market favoring sellers below 4.0 and buyers above 6.0; the figure measures pace, not price.
- Single-month figures are noisy (62 Boulder single-family sales in August, after 83 in July and 112 in June; the month median moved from $1,355,000 to $1,157,500 across those two releases while the year-to-date median moved by $100); we lead with year-to-date.
- Net-new supply. Boulder issues building permits annually but adds close to zero net-new single-family homes because construction is largely scrape-and-replace; the price-relevant supply is the existing stock changing hands.
- What we do not publish: a months-of-supply or median figure for the $800K–$1.5M band. No public source breaks it out; a direct IRES broker pull is required. So we label the town figure honestly and refuse to invent a band figure.
- A repeat-sales index (which tracks the same homes selling twice and so controls for changes in what sold) separates value from mix. The FHFA House Price Index publishes two quarterly for the Boulder metro area (Boulder County), an all-transactions index and an expanded-data index, and they can disagree in a single quarter.
Get the monthly Boulder read.
Real MLS numbers, and the basis they're actually measured on, about once a month. Unsubscribe any time; see our privacy policy.
See also: the Boulder market and neighborhood hub · the buy-before-you-sell playbook · bridge loan vs. sale contingency · the Boulder vs. Longmont comparison. External: CAR Local Market Update — Boulder (IRES data) · Boulder County Assessor.
Daniel Hsieh is a licensed Colorado real estate broker with True North Boulder, brokered by eXp Realty. Market figures are month-old MLS data and are not a valuation of any specific home; verify any number against current IRES or county data before acting. This report is general market information, not lending, tax, or legal advice: confirm your specifics with your lender, CPA, or attorney.